GLOBAL FERTILIZER
&
PETROCHEMICAL MARKET REPORT
August 2026
Coverage:
Nitrogen • Ammonia • Sulfur • Phosphates • Potash • NPK • Methanol • Energy • Freight • Scenarios
Executive Summary
August public-data signal: World Bank monthly data showed Eastern European urea at USD 390.0/metric ton, DAP at USD 793.5/metric ton, TSP at USD 704.4/metric ton, and potassium chloride at USD 386.9/metric ton. Regional gas references diverged sharply, reinforcing the need to separate market context from executable supplier quotations.
| Market | August public indicator | Verified anchor | Interpretation |
|---|---|---|---|
| Urea | Monthly benchmark eased | World Bank: USD 390.0/metric ton | Eastern Europe monthly average; not a Persian Gulf spot quotation |
| DAP | Monthly benchmark increased | World Bank: USD 793.5/metric ton | Monthly reference; not an executable cargo offer |
| TSP | Monthly benchmark decreased | World Bank: USD 704.4/metric ton | Monthly reference; product and basis differ from DAP and MAP |
| Potash | Monthly benchmark decreased | World Bank potassium chloride: USD 386.9/metric ton | Separate from producer guidance and realized prices |
| Methanol | Regional posted prices diverged | Methanex: USD 1,480 / 550 / 525 per metric ton | Posted references; not realized transaction prices |
| Energy | Regional gas costs diverged | World Bank: USD 2.77–21.11/MMBtu | Production economics remain region-specific |
| Freight | Use shipment-specific quotations | No unlicensed freight series reproduced | Compare vessel, parcel, route, insurance and laycan |
Executive priorities
- Treat India’s tender calendar as the single most important short-term price driver for urea, and size coverage decisions around tender timing rather than headline FOB levels alone.
- Separate commodity price, freight, insurance, and financing in every landed-cost decision, and continue to distinguish nominal production from executable, deliverable supply.
Management interpretation of the month
A third lesson concerns policy as a market variable in its own right. India’s proposed 20% subsidy on sulfur and sulphuric acid import costs, announced on 14 August, does not change the international price of sulfur, but it does change the price that domestic Indian phosphate producers effectively pay, and therefore changes their production incentives independent of the seaborne market. Reports that treat only seaborne benchmarks as the complete picture will increasingly miss policy-driven demand effects of this kind.
2. Macroeconomic and Energy Context
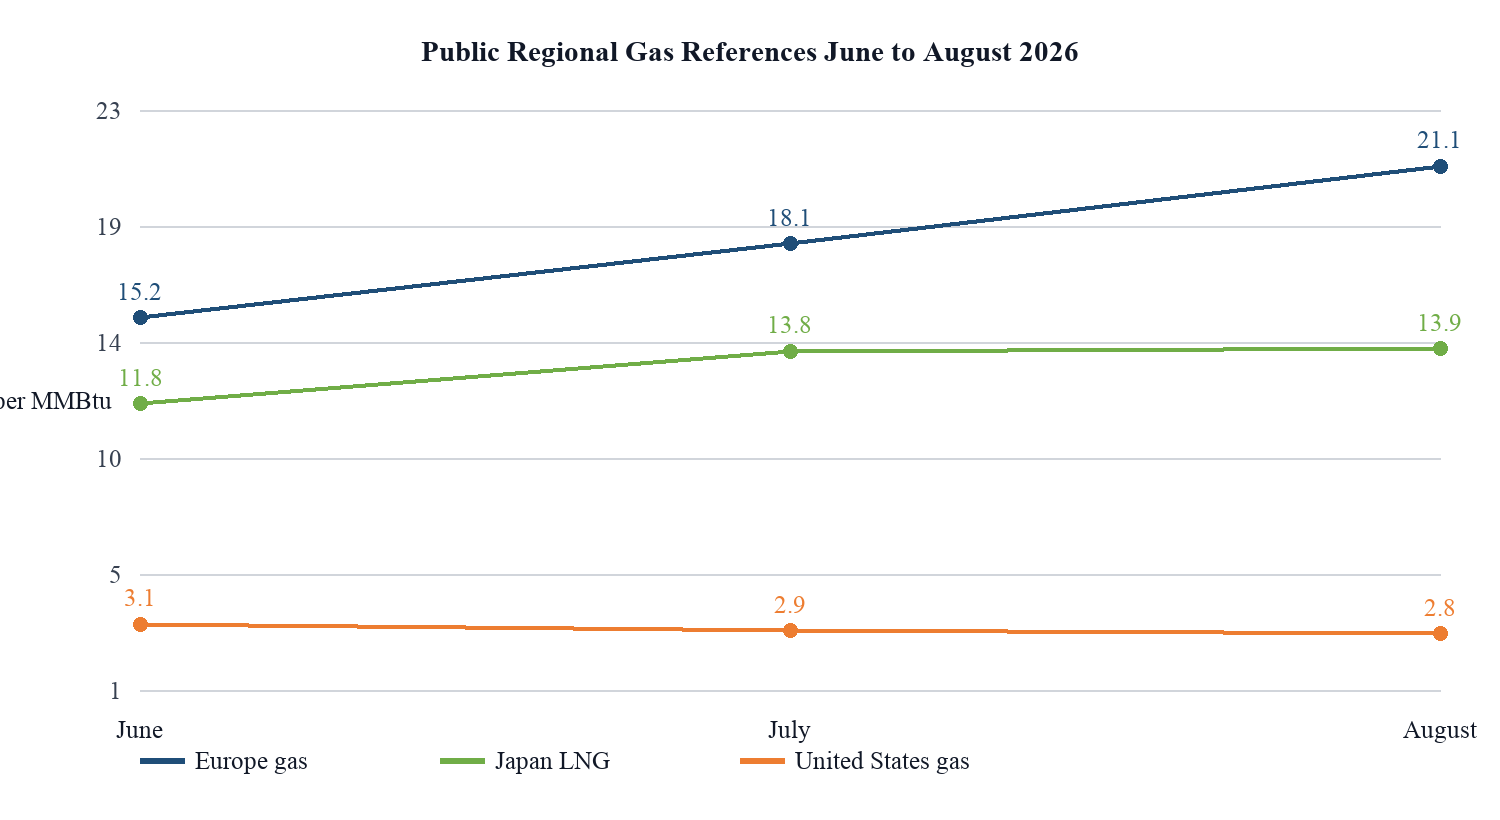
Figure 1. Public regional gas references, June–August 2026
Source:
World Bank Pink Sheet, September 2026
The IMF’s most recent published update, the July 2026 World Economic Outlook Update, continued to project global growth of 3.0% in 2026 and 3.4% in 2027, figures the Fund described as “broadly unchanged cumulatively” from its April 2026 World Economic Outlook (IMF, World Economic Outlook Update, July 2026). The Fund attributed the drag on growth primarily to a “war shock weighing on energy importers and vulnerable economies,” even as demand linked to artificial intelligence investment continued to lift economies integrated into the global technology value chain (IMF, World Economic Outlook Update, July 2026). No newer IMF update had been published by the close of the August reporting window; the July figures therefore remain the most current authoritative global growth reference for this report.
| Indicator | Verified value | Commercial relevance |
|---|---|---|
| United States natural gas, August 2026 | USD 2.77/MMBtu | Public monthly benchmark; not a plant contract |
| European natural gas, August 2026 | USD 21.11/MMBtu | Public monthly benchmark; compare on an energy basis |
| Japan LNG, August 2026 | USD 13.94/MMBtu | Different regional and contractual basis |
| Maize, August 2026 | USD 224.0/metric ton | Public reference; not local farm-gate revenue |
| Soybeans, August 2026 | USD 482.0/metric ton | Public reference; not local farm-gate revenue |
Public energy comparison: World Bank monthly data show August 2026 natural gas prices at USD 2.77/MMBtu in the United States, USD 21.11/MMBtu in Europe, and USD 13.94/MMBtu for LNG in Japan. These references use different regional and contractual bases.
Energy geography and producer competitiveness
Macroeconomic demand effects
The IMF’s continued 3.0%/3.4% growth projection for 2026/2027 supports a baseline expectation of steady, rather than contracting, global nutrient demand (IMF, World Economic Outlook Update, July 2026). As in July, the distribution of that growth matters more than the headline figure: energy-importing economies and financially constrained agricultural markets continue to face a materially different affordability position than energy-exporting economies or those with stronger fiscal support.
3. Nitrogen Market
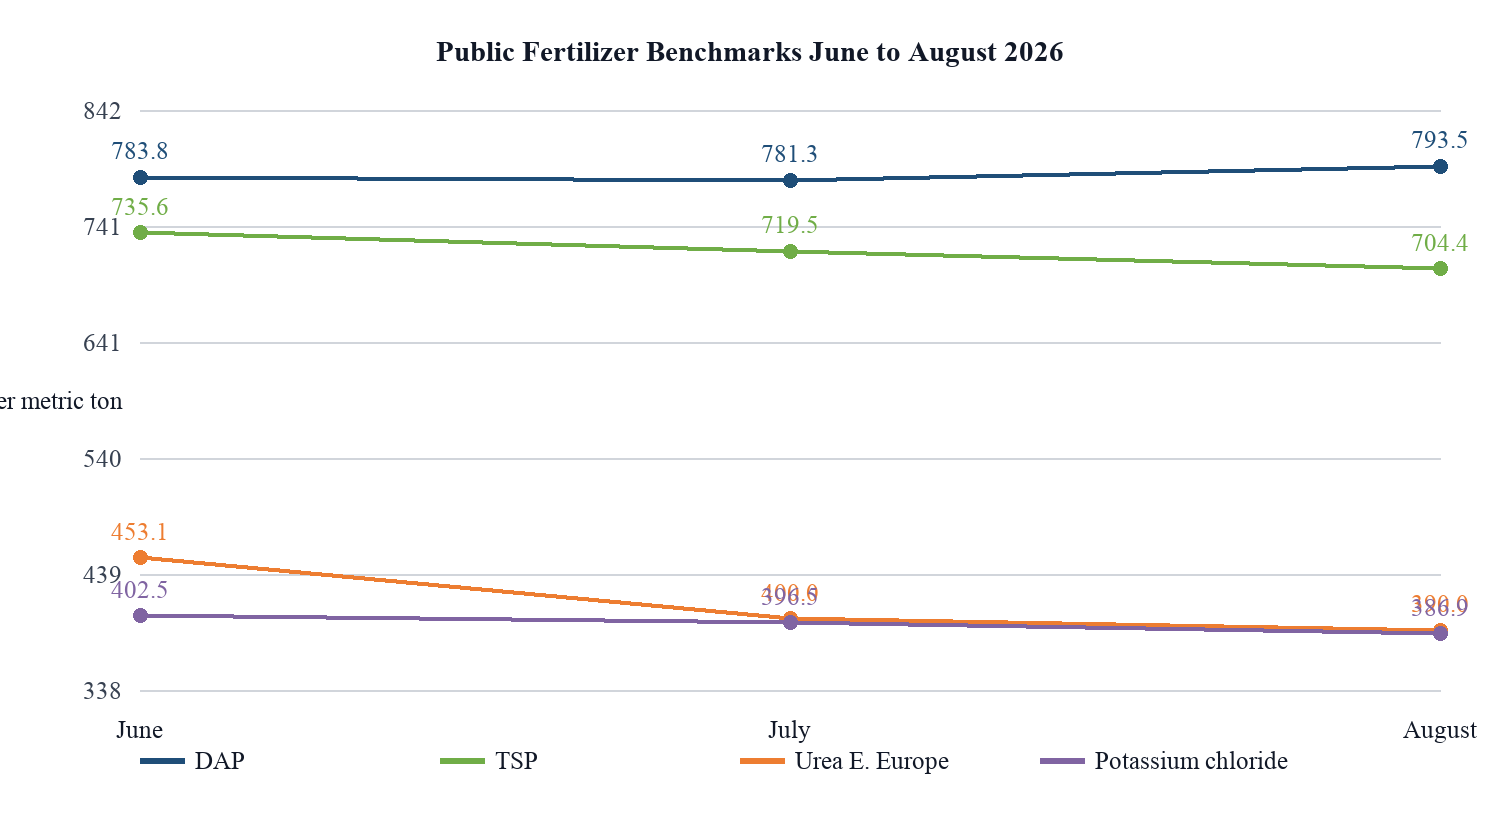
Figure 2. Public fertilizer benchmarks, June–August 2026
Source: World Bank Pink Sheet, September 2026
Public benchmark anchor: the World Bank Pink Sheet records the August 2026 monthly average for Eastern European urea at USD 390.0/metric ton, down from USD 400.0/metric ton in July. This monthly series does not represent spot transactions in the Persian Gulf, Brazil, China, or India.
Regional reading
Quality control: No unsupported NPK-style synthetic price series is inferred from urea. Each benchmark remains tied to its stated origin, product, and delivery basis, consistent with the methodology used throughout this report series.
4. Ammonia Market
No licensed, publicly reusable regional ammonia price series for August 2026 was identified for this edition. The report therefore excludes exact regional spot assessments and uses public company announcements only for capacity and investment context. Procurement decisions require current supplier quotations.
Regional ammonia dynamics
Demand structure and production economics
Ammonia outlook: September–October
Ammonia trade routes and contract structures
Low-carbon ammonia: strategic but not yet the spot driver
The August public announcements show that low-carbon and integrated ammonia-phosphate projects are planned on multi-year investment horizons. They provide capacity and project-timing context, not evidence of August spot prices or immediately available supply.
5. Sulfur Market
No proprietary sulfur price assessment, port-inventory database, or vessel-flow series is reproduced in this edition. Sulfur procurement analysis is limited to public policy information and transaction-specific supplier quotations.
Supply structure
Demand centers and downstream economics
Sulfur outlook: September–October
Persian Gulf producer system
China, Morocco and downstream operating rates
Sulfur inventory policy
6. Phosphates Market
| Driver | Public August evidence | Commercial interpretation |
|---|---|---|
| Urea benchmark | World Bank: USD 390.0/metric ton | Use as a monthly reference, not an executable cargo price |
| DAP benchmark | World Bank: USD 793.5/metric ton | Supports phosphate-cost monitoring without reproducing proprietary assessments |
| TSP benchmark | World Bank: USD 704.4/metric ton | Keep product and delivery basis separate from DAP and MAP |
| Energy inputs | World Bank regional gas references | Plant economics depend on actual gas contract and efficiency |
| Freight and insurance | No public benchmark series used | Obtain shipment-specific written quotations |
Commercial interpretation
DAP, MAP and phosphoric acid
Regional market structure
Phosphate outlook: September–October
Commercial response: track sulfur cost and freight alongside the finished phosphate benchmark rather than relying on the finished-product price alone, and monitor domestic subsidy programs (India in particular) as a determinant of regional demand independent of the seaborne price.
Phosphate rock and producer integration
India and subsidy economics
Brazil and MAP purchasing
7. Potash Market
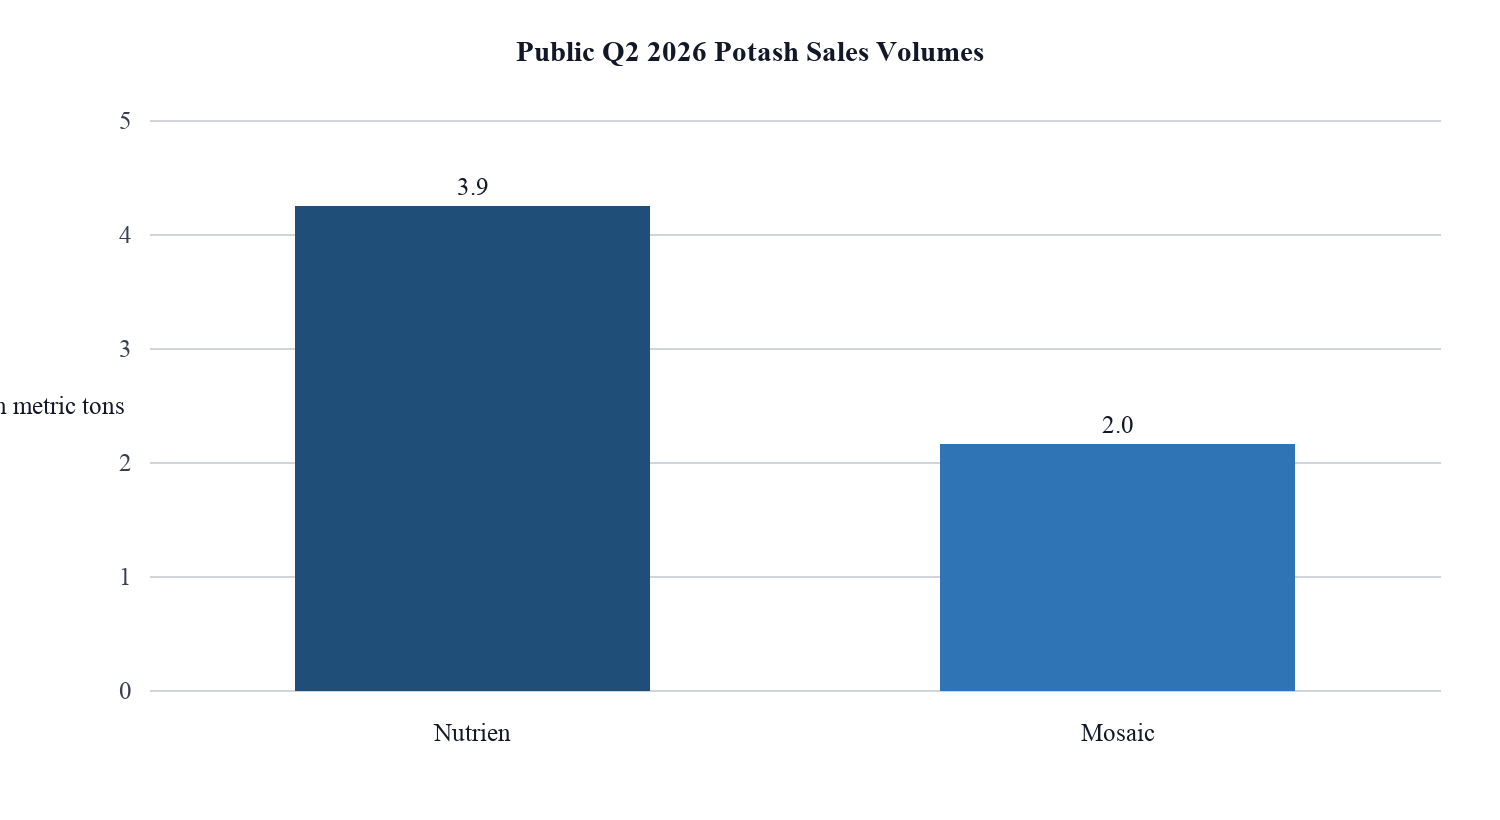
Figure 3. Public second-quarter 2026 potash sales volumes
Source:
Nutrien second-quarter 2026 results; Mosaic second-quarter 2026 results
Potash was the strongest-documented nutrient segment in the August dataset, supported by two sets of verified second-quarter 2026 producer results. Nutrien reported potash sales volumes of 3.943 million metric tons for the second quarter of 2026, split between 922,000 metric tons in North America and 3.021 million metric tons offshore, at an average net selling price of USD 267/metric ton (USD 295/metric ton in North America and USD 259/metric ton offshore) (Nutrien second-quarter 2026 results, published 5 August 2026). Nutrien also reported record first-half 2026 potash sales of 7.453 million metric tons, supported by record first-half production of 7.656 million metric tons, and raised its full-year 2026 potash sales guidance to a range of 14.2–14.8 million metric tons, citing robust offshore demand; the company maintained its forecast for global 2026 potash shipments at 74–77 million metric tons (Nutrien second-quarter 2026 results, published 5 August 2026).
Mosaic reported second-quarter 2026 potash sales of 2.0 million metric tons and production of 1.8 million metric tons, with an average MOP price of USD 275/metric ton on an FOB mine basis. The company guided full-year 2026 potash production to approximately 9.0 million metric tons with capital expenditure of USD 1.2 billion, and indicated a third-quarter 2026 outlook for potash sales of 2.0–2.2 million metric tons at USD 270–290/metric ton on an FOB mine basis (Mosaic second-quarter 2026 results, published 4 August 2026).
| Indicator | Value | Status |
|---|---|---|
| Nutrien Q2 2026 potash sales volume | 3.943 million metric tons | Reported |
| — of which North America | 0.922 million metric tons | Reported |
| — of which offshore | 3.021 million metric tons | Reported |
| Nutrien Q2 2026 average net selling price | USD 267/metric ton | Reported |
| — North America | USD 295/metric ton | Reported |
| — Offshore | USD 259/metric ton | Reported |
| Nutrien H1 2026 potash sales (record) | 7.453 million metric tons | Reported |
| Nutrien H1 2026 potash production (record) | 7.656 million metric tons | Reported |
| Nutrien FY2026 potash sales guidance | 14.2–14.8 million metric tons | Guidance (raised) |
| Global 2026 potash shipment forecast (Nutrien) | 74–77 million metric tons | Forecast (maintained) |
| Mosaic Q2 2026 potash sales | 2.0 million metric tons | Reported |
| Mosaic Q2 2026 potash production | 1.8 million metric tons | Reported |
| Mosaic Q2 2026 MOP price (FOB mine) | USD 275/metric ton | Reported |
| Mosaic FY2026 potash production guidance | 9.0 million metric tons | Guidance |
| Mosaic FY2026 capital expenditure guidance | USD 1.2 billion | Guidance |
| Mosaic Q3 2026 potash sales outlook | 2.0–2.2 million metric tons | Outlook |
| Mosaic Q3 2026 MOP price outlook (FOB mine) | USD 270–290/metric ton | Outlook |
Potash benchmark reference: the World Bank’s Pink Sheet put the August 2026 monthly average potash price (muriate of potash, standard grade, FOB Vancouver) at USD 386.9/metric ton, down from USD 396.5/metric ton in July 2026 (World Bank Commodity Markets, Pink Sheet, September 2026 edition). This is combined below with verified second-quarter 2026 results and forward guidance from Nutrien and Mosaic, and with Mosaic’s reported USD 275/metric ton fob-mine realization, to give a complete picture of August potash pricing across benchmark, producer-realized, and forward-guidance measures.
Supply concentration and trade flows
Potash supply remains concentrated in Canada, Russia, Belarus, China, Israel, Jordan, and a smaller group of European and Asian producers. New mine capacity requires long lead times and substantial capital, so incumbent producers retain considerable influence over the market through operating discipline rather than through new supply. Canadian exports remain central to seaborne trade; Russian and Belarusian volumes continue to reach international markets, though the commercial chain may involve additional steps for banking, insurance, documentation, and sanctions compliance.
The persistence of alternative trade routes reduces the probability of a severe global shortage but does not remove regional premiums. A cargo delivered by rail into China carries different economics than material delivered to Brazil, Southeast Asia, or an inland North American market. Logistics concentration — railways, dedicated terminals, and long ocean routes — remains a structural vulnerability that Nutrien’s and Mosaic’s record-volume results do not eliminate, even as both producers point to strong operating performance (Nutrien second-quarter 2026 results, published 5 August 2026; Mosaic second-quarter 2026 results, published 4 August 2026).
Demand centers and agronomic resilience
Potassium supports water regulation, root development, nutrient transport, stress tolerance, and crop quality. Farmers can temporarily draw down soil reserves, making short-term demand more discretionary than nitrogen demand, but sustained under-application reduces soil fertility and eventually constrains yield. This produces a recurring replenishment cycle that tends to follow large harvests.
Brazil, China, India, Southeast Asia, and North America remain the principal demand centers. Brazil’s import dependence and large soybean and maize planted areas make it strategically important, though credit conditions and exchange rates influence the timing of purchases. Plantation crops support Southeast Asian demand. China and India continue to rely on contract negotiation and inventory management, while North American consumption tracks application windows and dealer stock positioning. Nutrien’s characterization of offshore demand as “robust” in raising its full-year sales guidance is consistent with steady replenishment demand across these regions (Nutrien second-quarter 2026 results, published 5 August 2026).
MOP, SOP and affordability
Muriate of potash remains the dominant product for broad-acre crops. Sulfate of potash serves chloride-sensitive, high-value crops and typically commands a premium owing to its smaller production base and specialty demand profile. The two products should not be treated as interchangeable price benchmarks.
Potash retains a relative affordability advantage because MOP production does not depend on natural gas, ammonia, or sulfur as major feedstocks, unlike nitrogen and much of the phosphate complex. Mosaic’s reported MOP price of USD 275/metric ton on an FOB mine basis illustrates this comparatively contained cost structure (Mosaic second-quarter 2026 results, published 4 August 2026). Nevertheless, farm economics are evaluated in local currency and against crop revenue; high interest rates, weak commodity prices, or currency depreciation can delay applications even when potash is inexpensive relative to nitrogen and phosphate.
Potash outlook: September–October
- Base case: stable-to-firm conditions, with Nutrien’s raised full-year sales guidance and Mosaic’s steady third-quarter outlook both pointing to adequate supply and firm offtake (Nutrien second-quarter 2026 results, published 5 August 2026; Mosaic second-quarter 2026 results, published 4 August 2026).
- Bull risks: stronger Brazilian or Southeast Asian demand, Canadian logistics constraints, or renewed sanctions-related disruptions to Russian and Belarusian volumes.
- Bearish risk: delayed grower buying, weaker crop prices, or rising Russian and Belarusian availability pressuring offshore netbacks.
- Commercial response: maintain normal coverage, track producer guidance updates each quarter, and use licensed spot benchmarks for price-sensitive negotiations rather than the directional data presented here.
Canada and Canpotex logistics
Canadian potash moves from Saskatchewan mines through a highly integrated rail and terminal system. Offshore marketing requires dependable railcars, storage, and adequate capacity at Pacific or Atlantic ports. Strong producer sales commitments can tighten prompt availability even when mine production is running at record levels, as illustrated by Nutrien’s simultaneous record first-half production and record first-half sales (Nutrien second-quarter 2026 results, published 5 August 2026).
Canpotex provides scale and destination reach, but the concentration of export infrastructure creates exposure to rail disruptions, labor issues, weather, wildfires, and terminal performance issues. Buyers should monitor producer guidance alongside logistics indicators rather than relying solely on annual shipment figures.
Nutrien’s and Mosaic’s guidance indicates substantial annual capacity — a combined potash sales guidance approaching 23–24 million metric tons across the two companies for 2026 — but annual figures do not guarantee any specific weekly cargo window. Contract commitments, scheduled maintenance, and destination allocation determine the promptness of supply at any given port or rail corridor.
Russia, Belarus, and sanctions complexity
Russian and Belarusian potash remain important to the global balance. Alternative ports, rail routes, and destination markets have helped these volumes remain broadly steady, limiting the risk of an absolute global shortage. However, the commercial chain may require enhanced due diligence on banks, insurers, vessels, owners, and documentation, as well as on applicable sanctions regimes.
Discounted FOB offers from these origins should be evaluated based on payment risk, the likelihood of delays, and resale restrictions. A cargo that cannot be financed or insured through the buyer’s counterparties is not equivalent to unrestricted supply, regardless of the headline discount.
Qualified legal and sanctions professionals must make compliance decisions. Market analysis of the kind presented in this report can identify exposure but cannot replace transaction-specific legal review.
Contract benchmarks and spot transparency
China and India often use major contract negotiations to establish reference points for Asian potash trade. Contract prices may cover large volumes and extended periods, while spot transactions reflect immediate regional balances; the two should not be combined without acknowledging the differences in timing and terms. Nutrien’s and Mosaic’s quarterly average selling prices — USD 267/metric ton and USD 275/metric ton respectively — are company-wide averages across destinations and grades, not a single benchmark price for any one route (Nutrien second-quarter 2026 results, published 5 August 2026; Mosaic second-quarter 2026 results, published 4 August 2026).
Producer netbacks also vary by freight and product grade. Standard MOP, granular MOP, and SOP serve different markets. A published quarterly average or forward guidance range can guide sentiment, but it does not create a complete weekly curve for Vancouver FOB, Brazil CFR, or Southeast Asia CFR.
8. NPK and Compound Fertilizers
Compound fertilizers combine the economics of nitrogen, phosphate, and potash inputs, so their cost base moves with developments across all three markets covered elsewhere in this report. The August dataset does not include a licensed benchmark series for individual NPK grades, so this section again supports a directional, not numerical, assessment, supplemented by one verified policy development relevant to phosphate-linked formulations.
| Cost component | Public August indicator | NPK implication |
|---|---|---|
| Nitrogen/urea | World Bank urea: USD 390.0/metric ton | Confirm formula, grade, and delivered basis |
| Phosphate inputs | World Bank DAP: USD 793.5; TSP: USD 704.4/metric ton | Do not infer MAP or phosphoric acid prices |
| Potash | World Bank potassium chloride: USD 386.9/metric ton | Verify MOP or SOP grade and freight separately |
| Energy | United States gas USD 2.77; Europe gas USD 21.11/MMBtu | Conversion economics remain regional |
| Freight/insurance | Shipment-specific quotation required | Separate route, vessel, cover and financing terms |
Recommended buying approach: compare formulations on delivered nutrient cost, use staggered coverage, and verify whether quoted grades are chemically equivalent before making cross-market comparisons.
Formulation economics
An NPK grade is not a single commodity. The cost of a 15-15-15, 20-20-0, or crop-specific formulation depends on nutrient concentration, raw material selection, granulation route, fillers, additives, packaging, and plant scale. Two products carrying the same headline grade can have different physical quality, nutrient solubility, trace-element content, and delivered performance.
Regional demand and procurement
Buyers should calculate the cost per unit of available nutrient rather than compare only USD per metric ton across grades. They should also evaluate nutrient balance for the target crop and soil. A lower-priced grade can be more expensive in practice if it supplies unwanted nutrients or requires additional application passes and logistics.
NPK outlook and risk controls
- Use raw-material escalation clauses only when the underlying indices and formulas are transparent.
- Verify grade, nutrient solubility, granule strength, moisture content, packaging, and tolerance before comparing offers.
- Stagger purchases for volatile raw materials, while securing critical seasonal volumes early enough to protect delivery.
- Do not publish synthetic market prices without a verified benchmark series for the exact grade and basis.
Production routes and quality variables
Compound fertilizers can be produced through chemical granulation, steam granulation, bulk blending, or other processes. Chemical granulation can improve nutrient distribution within each granule, while bulk blends rely on compatible particle size and density to reduce segregation. The correct choice depends on crop, distribution system, application equipment, and price.
Quality specifications should address total and available nutrients, moisture, particle-size distribution, crushing strength, caking, dust, chloride, micronutrients, and packaging. Storage climate and voyage duration can materially affect condition on arrival. A low headline price does not compensate for segregation, caking, or nutrient non-conformance discovered at discharge.
Inspection should be designed around risk. Pre-shipment certificates, independent sampling, loading supervision, and discharge claims procedures are particularly important for new suppliers or long voyages, and become even more important when input costs — such as sulfur — are in flux due to policy rather than pure supply-demand dynamics.
Blender margin and working capital
The amount of raw materials also increases working capital requirements. Procurement must balance minimum economic parcel size against storage, financing, and formulation flexibility. Excess stock of one nutrient can force a blender to produce suboptimal grades or delay purchases of another nutrient, a risk that is amplified when a major buying market’s cost base is subject to a pending policy change.
A formulation margin model should therefore track nutrient cost, conversion, packaging, loss, finance, freight, and sales price by grade, and be updated as policy developments, such as the Indian subsidy proposal, move toward implementation or are set aside. Generic percentage assumptions are insufficient for final commercial decisions.
9. Methanol and Petrochemical Feedstocks
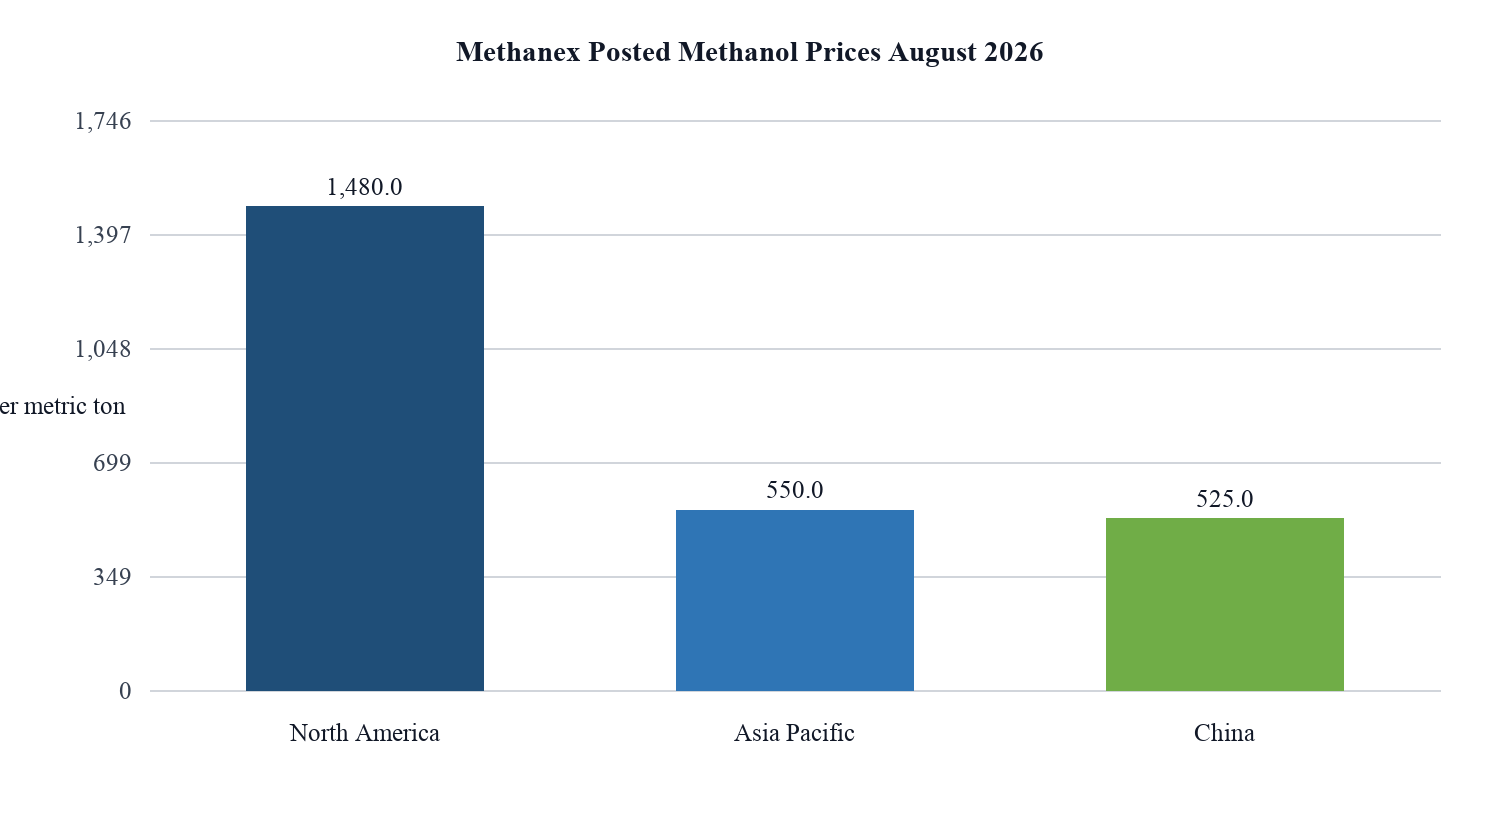
Figure 4. Methanex posted methanol prices for August 2026
Source:
Methanex historical pricing workbook
| Region | Posted price | Basis/validity |
|---|---|---|
| North America | USD 1,480/metric ton | August 2026 historical posted reference |
| Asia Pacific | USD 550/metric ton | August 2026 historical posted reference |
| China | USD 525/metric ton | August 2026 historical posted reference |
Interpreting posted methanol prices
The wide regional spread reflects differences in pricing systems and supply-demand conditions rather than a single global methanol price. China has a large domestic coal-based methanol industry and a liquid spot market. Asia Pacific import pricing reflects regional contracts and ocean freight. North America combines domestic production, imports, and contract structures that have historically supported a materially higher posted level. Europe’s quarterly euro-denominated reference introduces both a different validity period and foreign-exchange exposure relative to the three USD-denominated regions.
Feedstocks and downstream demand
Downstream demand includes formaldehyde, acetic acid, MTBE, fuel applications, solvents, and methanol-to-olefins conversion. Changes in construction, automotive activity, gasoline blending, and the economics of Chinese olefins can therefore affect methanol demand independently of fertilizer market conditions. The product is included in this report as a feedstock and energy-linked comparator rather than as a fertilizer in its own right.
Near-term methanol watchpoints
- Chinese coal economics and methanol-to-olefins operating rates.
- Natural-gas availability and outages at major export plants.
- Currency conversion for European contracts; no USD comparison should be made without an explicit dated FX rate.
Regional production economics
Methanol commercial risk
Currency remains another source of risk. European references are denominated in euros, while many feedstocks, freight contracts, and global comparisons are denominated in USD. Converting a quarterly euro price with an undated exchange rate can create a misleading chart, so this report leaves the European value in its published currency, consistent with the approach taken for the July edition of this report.
For internal reporting, posted price, estimated discount, freight, duty, storage, and financing should be shown separately. This creates a traceable bridge from the public Methanex reference to an expected landed or realized value for any specific cargo or contract.
10. Freight and Logistics
This section excludes broker freight sheets, vessel line-ups, and subscription route assessments. Public government and canal announcements provide policy context; executable freight must be confirmed for the named vessel, parcel, route, laycan, insurance, and destination.
| Public logistics indicator | August announcement | Commercial use |
|---|---|---|
| UAE–Iran commercial relationship | UAE official statement published 19 August | Run transaction-specific counterparty, bank, and sanctions review |
| Panama Canal | September slot changes announced during August | Confirm booking and route suitability with the carrier |
| Persian Gulf shipments | No public freight-rate series reproduced | Request written vessel, insurance, laycan and demurrage terms |
| Port readiness | No generic delay assumption used | Verify berth, storage, handling and inland evacuation for each destination |
Landed-cost discipline
Preserve the term “Persian Gulf” consistently in commercial and analytical documentation.
Red Sea, Black Sea and alternative routing
Freight contracting priorities
- Match parcel size and vessel class to the terminal’s capabilities and the expected route, factoring in the tightened Panama Canal slot availability from September for any Americas-bound routing.
- Maintain an alternative logistics plan for critical seasonal cargoes, including non-Persian Gulf origins and, where feasible, non-Rhine-dependent inland routing.
Vessel classes and product compatibility
Urea, sulfur, phosphates, potash, and NPK are generally transported in dry bulk vessels, but parcel size, stowage, contamination sensitivity, and terminal equipment vary. Gas carriers transport ammonia, while chemical tankers transport methanol. Freight comparisons must therefore remain within compatible vessel and cargo systems, and this discipline matters more than usual in August given how differently each product class has been affected inside the Persian Gulf — sulfur and ammonia loadings collapsed by far larger margins than urea, which retained at least some vessel movement each week.
Larger vessels can lower unit cost but require sufficient cargo volume, port draft, storage, and discharge capacity; this trade-off becomes sharper when a large parcel also represents a larger tonnage exposed to Persian Gulf holding risk. Smaller parcels offer flexibility but may carry a higher USD-per-metric-ton rate. Split cargoes can optimize logistics but add complexity in nomination, quality, and laytime, particularly where a vessel’s crossing window is itself uncertain.
Insurance, finance and documentation
Freight monitoring dashboard
- Indicative freight by route, parcel size, and vessel class, with explicit tracking of the spread between the low and high end of each quoted range.
- Vessel nominations, arrival dates, and actual strait crossings, rather than nominal loading programs.
- Rhine gauge readings at Kaub and ARA-Karlsruhe barge freight, for any cargo dependent on Rhine inland distribution.
- Panama Canal daily transit-slot utilization ahead of the September cap for any Americas West Coast- or Chile-bound routing.
11. Regional Market Synthesis
| Region | Public August anchor | Decision implication | Near-term watchpoint |
|---|---|---|---|
| Public August anchor | World Bank US gas USD 2.77/MMBtu | Cost context remains favorable relative to Europe | Supplier allocation and autumn demand |
| Decision implication | World Bank Europe gas USD 21.11/MMBtu | Energy exposure remains materially higher | Gas procurement and inland delivery |
| Near-term watchpoint | UAE official statement on dealings with Iran | Apply transaction-specific legal and banking checks | Official government notices |
| North America | World Bank and public producer data only | Do not infer export availability from unlicensed reports | Customs and official policy releases |
| World Bank US gas USD 2.77/MMBtu | Public monthly benchmarks do not equal landed offers | Compare freight, credit and destination costs | Crop-season procurement timing |
| Cost context remains favorable relative to Europe | Public RCF tender announcement | Separate invitation volume from awards and arrivals | Official tender and policy notices |
| Supplier allocation and autumn demand | No proprietary regional series used | Use executable offers and destination requirements | Currency and crop economics |
| Europe | No proprietary port-delay series used | Verify port and inland capacity cargo by cargo | Berth and storage confirmation |
| World Bank Europe gas USD 21.11/MMBtu | |||
| Energy exposure remains materially higher | |||
| Gas procurement and inland delivery | |||
| Persian Gulf | |||
| UAE official statement on dealings with Iran | |||
| Apply transaction-specific legal and banking checks | |||
| Official government notices | |||
| China | |||
| World Bank and public producer data only | |||
| Do not infer export availability from unlicensed reports | |||
| Customs and official policy releases | |||
| Brazil | |||
| Public monthly benchmarks do not equal landed offers | |||
| Compare freight, credit and destination costs | |||
| Crop-season procurement timing | |||
| India | |||
| Public RCF tender announcement | |||
| Separate invitation volume from awards and arrivals | |||
| Official tender and policy notices | |||
| Southeast Asia | |||
| No proprietary regional series used | |||
| Use executable offers and destination requirements | |||
| Currency and crop economics | |||
| Africa | |||
| No proprietary port-delay series used | |||
| Verify port and inland capacity cargo by cargo | |||
| Berth and storage confirmation |
Americas
Europe, Asia and the Persian Gulf
Africa and food-security considerations
Regional comparison: what changes the landed result
Country watchlist for September and October
12. Scenario Outlook
The outlook is framed qualitatively because the numerical probability weights in the earlier draft were internal estimates and did not follow an approved forecasting methodology.
| Scenario | Publicly observable conditions | Expected exposure | Management posture |
|---|---|---|---|
| Base case | Public benchmarks remain near August levels | Regional cost and freight differences persist | Stagger coverage and require executable offers |
| Stress case | Official restrictions or route constraints intensify | Freight, financing and replacement-cost risk rises | Use approved alternative routes and defined safety-stock triggers |
| Relief case | Official restrictions ease, and carrier capacity improves | Logistics premiums may decline | Avoid over-covering; reprice landed alternatives |
Leading indicators
- Nutrien and Mosaic quarterly guidance revisions on potash volumes
- India’s sulfur/sulphuric-acid subsidy proposal and its eventual approval status
Base-case narrative
Stress and relief cases
Scenario governance
Do not assign numerical probabilities unless management approves a repeatable forecasting method.
Product behavior by scenario
Trigger matrix
Financial effects of the scenarios
13. Strategic Conclusions and Recommendations
| Priority | 0–30 days | 30–90 days | 90+ days |
|---|---|---|---|
| Procurement | Map supplier, origin, and delivery exposure | Qualify alternatives using public evidence and executable quotations | Maintain a diversified sourcing portfolio |
| Inventory | Confirm critical stock and consumption data | Set product-specific reorder triggers | Review resilience targets quarterly |
| Freight | Separate freight, insurance and delay clauses | Pre-negotiate route and insurer options | Maintain a multi-corridor playbook |
| Finance | Review counterparty, FX and working-capital exposure | Expand approved financing options | Integrate landed-cost risk limits |
| Intelligence | Use official and publicly accessible sources | Maintain a source register and archive | Audit publication rights before each report |
Product-specific guidance
| Product | Use the World Bank's August monthly reference as market context and obtain executable regional quotations to inform procurement decisions. |
|---|---|
| Urea | Do not publish an August spot-price series without a licensed or clearly reusable public source; manage coverage through supplier quotations. |
| Ammonia | Use supplier quotations and public policy announcements; do not reproduce proprietary assessments or inventory databases. |
| Sulfur | Model sulfur, ammonia, energy, and freight separately and keep product and delivery bases explicit. |
| DAP / MAP | Use World Bank monthly data and public releases from Nutrien and Mosaic for context, not as a guarantee of spot availability. |
| Potash | Buy on verified nutrient content, specification, and delivered cost rather than generic grade labels. |
| NPK | Use Methanex postings as reference values and confirm discounts, freight, and contract terms separately. |
| Methanol |
Procurement architecture
Inventory and financial management
Market-intelligence operating model
Executive action checklist
- Require landed-cost decomposition for major purchases, isolating the sulfur/freight/insurance components from the base commodity price.
- Track the status of India’s proposed 20% sulfur/sulphuric-acid import subsidy and its potential effect on phosphate producer economics and pricing.
- Retain licensed benchmark access for negotiations where exact spot values are commercially material.
Governance and decision rights
Supplier and counterparty scorecard
Counterparty limits should incorporate both financial exposure and operational dependence. A small supplier can be critical if it provides a unique grade or route; a large supplier can create concentration through multiple contracts, particularly where several counterparties ultimately depend on the same constrained corridor. Parent guarantees, letters of credit, and insurance reduce some risks but do not replace operational due diligence, especially where insurers themselves may be reassessing appetite for Persian Gulf-linked risk.
Scorecards should use recent evidence and be updated after every material cargo. The purpose is to inform allocation and negotiation, not merely to rank suppliers once per year, and August’s rapid shifts in both commodity price and shipping conditions make timely updates more important than usual.
Implementation roadmap
Data governance should be implemented alongside commercial actions. Licensed benchmark access, source archives, unit normalization, and version control prevent future reports from mixing illustrative and verified figures. Charts should be generated directly from controlled data tables.
14. Detailed Country and Trade-Flow Profiles
China: production, consumption, and export optionality
India: tender-led procurement and subsidy exposure
Brazil: import dependence, credit, and seasonality
On the policy side, the Brazilian government approved a rule, published on 20 August 2026 and effective for six months, granting priority unloading at public ports to shipments of imported fertilizer. The measure is explicitly intended to support the 2026-27 crop season by reducing the risk that congestion or queuing delays fertilizer arrivals during the critical application window. For importers and logistics planners, the rule should ease — though not eliminate — the berthing and discharge uncertainty that has periodically disrupted Brazilian import programs in prior seasons.
United States and Canada
Mosaic reported second-quarter 2026 potash sales of 2.0 million metric tons at USD 275/metric ton FOB mine and guided full-year production to approximately 9.0 million metric tons. Nutrien reported first-half potash sales of 7.453 million metric tons and raised full-year sales guidance to 14.2–14.8 million metric tons. These public disclosures describe company results and guidance; they do not guarantee regional allocation, delivery timing, or executable spot prices. Sources: Mosaic; Nutrien
Morocco, North Africa, and the Persian Gulf
Southeast Asia, Africa, and emerging demand
15. Product Cost and Margin Mechanics
Ammonia and urea cost chains
Urea economics add carbon dioxide integration, conversion chemistry, granulation or prilling, storage, and loading to the ammonia base. Export margin should always be calculated from FOB realization less variable production, terminal, and commercial costs — not from a headline benchmark price alone. Delivered competitiveness then requires adding ocean freight, insurance, and destination charges, and this is where routing risk becomes decisive: when a corridor is disrupted or freight rates spike, a structurally low-cost Persian Gulf plant can temporarily lose its delivered-cost advantage to a higher-cost Atlantic Basin or North American origin serving the same destination. Traders modeling delivered urea competitiveness in Brazil or South Asia this month should therefore use current freight rates rather than a seasonal average.
Sulfur and phosphate cost transmission
DAP and MAP margins require a full accounting of phosphate rock, sulfur, ammonia, utilities, conversion yield, maintenance, and freight. Integrated producers — those controlling rock, sulphuric acid, and finished fertilizer production within one corporate structure — can transfer value between stages rather than optimizing each stage independently, allowing them to sustain output through periods of high sulfur costs that would force a non-integrated acid or fertilizer producer to curtail production. This distinction matters directly for August: OCP’s decision to redirect volumes toward the US rather than absorb the full sulfur-cost impact on Brazil-bound cargoes reflects exactly this kind of integrated-producer optimization, in which destination mix — not just output level — becomes a lever for managing feedstock cost pressure.
Potash mining and delivered economics
Potash cost structures include mining or solution mining, processing, maintenance, royalties, taxes, rail haulage, and terminal charges. Mine cash cost can be low relative to delivered value, but the distance from Saskatchewan, Russia, or Belarus to major consuming markets makes logistics a substantial share of the final landed price; product grade and granulation specification add further differentiation on top of the base mining and processing cost. Producer guidance such as Mosaic’s reported USD 275 per metric ton FOB-mine realization for its 2.0 million metric tons of Q2 2026 sales offers a useful reference point, but buyers should recognize that FOB-mine pricing excludes the rail and ocean-freight components that typically make up a large share of delivered cost into offshore markets (Mosaic second-quarter 2026 results, published 4 August 2026).
Producer discipline matters in potash more than in most other fertilizer products because supply is geographically concentrated and new mine capacity takes years, sometimes a decade or more, to develop. Annual nameplate capacity, therefore, does not mean all tonnes are available at every price point; contract allocation strategy, planned and unplanned maintenance, railcar availability, and destination-market strategy all influence how much prompt tonnage actually reaches the seaborne market in a given quarter. Nutrien’s move to raise full-year 2026 guidance to 14.2-14.8 million metric tons after a record first-half of 7.453 million metric tons signals continued high utilization across the major producers, which should be read as broadly supportive of supply availability into the fourth quarter, even as buyers continue to negotiate delivered price on a destination-by-destination basis (Nutrien second-quarter 2026 results, published 5 August 2026).
NPK formulation and blending margin
A finished NPK cost model should begin with the precise recipe and nutrient assay rather than a generic raw-material cost share. Raw-material tonnage must be adjusted for nutrient concentration, moisture content, and expected process loss before it can be converted into a meaningful cost-per-nutrient-ton figure. Conversion energy, steam, utilities, additives, packaging, labor, quality control, finance, and freight must then be layered on top. Blenders who rely on published percentage cost breakdowns as anything more than an initial screening tool risk systematically mispricing formulations whose raw-material mix diverges from the generic assumption.
Methanol realization bridge
Methanol posted prices function only as starting references. Realized value can diverge from the posting through negotiated discounts, customer-specific formulas, freight, terminal costs, product loss in transit and storage, and currency effects. A North American contract posting and a Chinese spot assessment are not directly comparable without a clear understanding of each market’s respective conventions for quotation basis, payment terms, and included costs.
Producer margin in methanol depends on the underlying feedstock — natural gas or coal — plant conversion efficiency, operating rate, and destination market. Downstream demand from methanol-to-olefins conversion, formaldehyde production, acetic acid manufacturing, and fuel-blending applications all influence the balance that ultimately determines realized price. Commercial reporting for methanol should therefore explicitly separate posted, spot, contract, and net realized prices, since conflating these categories — as with the NPK inventory-versus-manufacturing distinction above — tends to overstate or understate true trading performance.
Sensitivity analysis
Sensitivity models should vary one factor at a time, and then in combination, for product price, feedstock gas cost, sulfur cost, ammonia cost, freight rate, foreign-exchange rate, interest rate, and plant utilization. The objective of such modeling is to identify which variable, or combination of variables, can breach a margin or liquidity threshold — not to imply a level of forecasting precision that the underlying markets do not support. August’s sulfur-driven margin pressure on phosphate producers is a practical example of exactly this kind of single-variable stress: a feedstock cost shock that materially affects downstream margin even where finished-product demand and pricing remain stable.
For major purchases, the buyer should calculate delivered cost under base, stress, and relief scenarios, varying freight and FOB assumptions independently rather than moving them together. For production planning, management should compare the economics of continued operation, temporary curtailment, and substitution with imported intermediate products, using the same base/stress/relief framework applied on the buy side. Every sensitivity model output should state its source date, unit of measurement, Incoterm basis, and whether each input value is an observed market price or an internal assumption, so that downstream users of the analysis can distinguish fact from estimate at a glance.
16. Procurement and Contracting Playbook
Portfolio design
A resilient procurement portfolio combines base-load term contracts, formula-linked agreements, and tactical spot purchases. Term supply protects continuity of physical availability, formula-linked agreements share market risk between buyer and seller over the life of the relationship, and spot cargoes preserve flexibility and support ongoing price discovery. The appropriate mix among these three depends on the product's criticality to downstream operations, available storage capacity, typical lead time from order to delivery, and the depth and liquidity of the relevant spot market.
Diversification should be measured across origin, producing plant, loading port, shipping corridor, vessel class, financing bank, and cargo insurer — not merely across counterparty names. Multiple supply contracts provide little genuine risk reduction when they all depend on the same constrained route or the same chokepoint, as this report’s discussion of Persian Gulf shipping conditions illustrates. Allocation decisions among qualified suppliers should reward both competitive pricing and a demonstrated track record of execution, since a marginally cheaper offer from a supplier with a weak delivery history can prove considerably more expensive once delay, claims, and substitute-sourcing costs are included.
Pre-tender preparation
Before issuing an inquiry, the buyer should define product specification, permissible quantity tolerance, parcel size, loading or delivery window, destination handling capability, inspection requirements, payment terms, and any restrictions on acceptable origins. Ambiguity at this stage is the single most common cause of non-comparable bids and post-award disputes; a specification that leaves grade, granulation, or moisture tolerance open to interpretation invites offers that cannot be evaluated on a like-for-like basis.
The bid sheet issued to prospective suppliers should require a complete price basis: Incoterm, named port or delivery point, whether freight is included, insurance arrangement, applicable taxes and duties, currency of settlement, offer validity period, and any escalation mechanism. Where route risk is material — as it currently is for Persian Gulf-origin cargoes — suppliers should be required to disclose the producing plant, the loading terminal, and the expected vessel class, so that the buyer can assess routing and chokepoint exposure before, rather than after, contract award.
Offer normalization and award
Offers received in response to a tender or inquiry should be normalized to a common delivered basis and a common nutrient basis before comparison. This normalization must account for differences in offer quality, freight to the actual discharge point, insurance, financing costs, duties, port handling costs, inland transport to the final destination, and expected in-transit loss. A risk-adjusted comparison can also quantify the expected cost of delay or non-performance for each offer, provided the probability and cost assumptions underlying that adjustment are made transparent to all internal stakeholders reviewing the award.
Award decisions should record both the commercial and operational rationales in writing. Splitting volume across multiple suppliers can reduce counterparty concentration risk, but it may also increase per-unit freight costs or complicate quality control at the receiving end, so the decision to split should be a deliberate trade-off rather than a default. The chosen award strategy should be explicitly linked to current inventory coverage and the availability of alternative supply, so that the rationale remains auditable if market conditions change materially before the cargo is delivered.
Essential contract clauses
Contracts should define, at minimum: product specification and tolerance, inspection method, sampling procedure, laycan, vessel nomination process, loading rate, discharge rate, demurrage and despatch terms, title transfer, risk transfer, payment mechanism, sanctions language, force majeure, safe-port warranty, deviation rights, and claims procedure. Ambiguity in any of these clauses is least costly when nothing goes wrong and most expensive precisely when a disruption occurs — which is exactly when the clause is actually tested.
Index-linked pricing provisions require a precise benchmark name, the specific publication that produces it, the unit of measurement, the averaging period used to derive the applicable price, the settlement currency, and an explicit fallback mechanism to be used if the assessment becomes unavailable during the life of the contract. Freight adjustment mechanisms, quality-premium or discount schedules, and tax treatment should all be documented in the contract itself rather than left to informal understanding between the commercial teams that negotiated the deal, since those individuals may not be the ones administering the contract when a dispute arises.
Performance and claims
Supplier performance should be tracked systematically against on-time loading, documentation accuracy and timeliness, product quality on arrival, quantity delivered against contract, responsiveness to buyer queries, and the speed and fairness of claims resolution. A formal claims procedure must specify the notice period within which a claim must be raised, the evidence required to substantiate it, and the independent inspection body or method to be used to resolve disputes over quality or quantity. Retained samples should be held in accordance with an agreed chain-of-custody procedure so that their evidentiary value is not later challenged on procedural grounds.
After each materially sized cargo, procurement, logistics, and quality teams should conduct a structured closeout review. Lessons learned regarding port performance, vessel suitability for the route and cargo type, documentation handling, and product condition on arrival should feed directly into the scorecards used for future supplier qualification and allocation decisions, so that the organization’s procurement capability compounds over successive cargoes rather than resetting with each new transaction.
Ethics, sanctions and compliance
Due diligence on any counterparty should cover corporate ownership and control structure, applicable sanctions regimes, anti-bribery and corruption exposure, identification of beneficial owners, vessel ownership and voyage history, and the full payment chain from buyer to ultimate beneficiary. Commercial urgency — a tight loading window, a favorable price that may not be repeated, or pressure to secure tonnage ahead of a competitor — does not remove or reduce these legal obligations. Where the legal position on a specific counterparty, vessel, or payment route is genuinely uncertain, the transaction should be escalated to qualified legal counsel before proceeding, rather than resolved through internal commercial judgment alone.
Compliance clauses within a contract do not substitute for pre-transaction screening; they document the parties’ agreement but do not, in themselves, verify that a counterparty, vessel, or payment channel is clean. Banks and insurers frequently apply screening policies that are stricter than the letter of the law requires, and their willingness to finance, process payment for, or insure a given transaction should be confirmed early in the transaction cycle, not assumed. Every compliance decision, and the information on which it was based, should be documented in a form that supports and provides evidence of the organization’s decision-making process, should it be reviewed later.
17. Inventory and Working-Capital Framework
Inventory segmentation
Inventory should be divided into operational stock, safety stock, strategic stock, committed transit, and optional supply. Operational stock supports normal production or sales. Safety stock covers delivery variability. Strategic stock protects against low-probability disruption. Transit stock is counted only based on realistic arrival probabilities.
Each product requires its own policy. Sulfur may be plant-critical but constrained by storage and safety. Urea is liquid in trade but volatile. Potash is relatively stable but long-haul. NPK has grade-specific obsolescence and caking. A single day-of-cover target is therefore inappropriate.
Reorder points and trigger bands
Reorder points should account for expected demand during lead time, lead-time variability, and the service target. Market triggers can temporarily raise or lower coverage bands. Confirmed route disruption, falling vessel departures, or supplier outage can justify additional safety stock; weaker demand and improving logistics can reduce it.
Triggers should be defined before a crisis. If management changes coverage without recorded evidence, the organization may repeatedly buy high and sell low. A formal band preserves discipline while allowing authorized exceptions. The same discipline that a mature framework applies to freight and demand triggers should also apply to abrupt counterparty or jurisdictional triggers: the announcement of a broad-based trade suspension between two markets, for example, is precisely the sort of externally imposed, non-gradual event that a pre-agreed trigger band is designed to accommodate without requiring an emergency policy debate in the moment.
Working-capital calculation
Working capital includes product value, freight, duties, inventory days, transit days, receivables, and payables. Higher prices and longer voyages create a compound effect: more cash is tied up in each metric ton for a longer period. Insurance and financing fees also rise.
Finance should forecast cash by cargo and product, not only by monthly aggregate. Letters of credit, margin deposits, prepayments, and delayed documents can create timing peaks. Liquidity should be secured before procurement windows become urgent. Where a planned production outage at a major supplier is publicly known well in advance — as with a multi-week turnaround schedule — working-capital planning has the advantage of lead time; the same discipline should still price in the possibility that a scheduled outage runs longer than announced, since maintenance windows are estimates rather than guarantees.
Inventory valuation and price risk
High-cost inventory is exposed when replacement values fall. The organization should separate physical security from speculative length. Back-to-back sales, price formulas, hedges where available, and measured coverage reduce inventory mismatch.
Valuation reports should distinguish realized margin, replacement margin, and accounting inventory effects. A profitable historical sale can conceal a weak replacement position, while an accounting loss can coexist with improved future purchasing economics. A market in which regional stock levels are falling sharply, as observed in sulfur during August 2026, can also see replacement cost move quickly in either direction as buyers react to headline inventory figures; valuation methodology should be able to isolate that effect from ordinary trading margin.
Storage and product integrity
Storage limits are both physical and financial. Urea and NPK require moisture and caking control. Sulfur requires fire, dust, and environmental management. Methanol requires appropriate tanks and safety systems. Potash quality can be affected by moisture and segregation.
Warehouse capacity, handling rate, bagging, blending, and discharge constraints should be incorporated into inventory strategy. Buying beyond usable capacity transfers risk from the market to operations.
Inventory governance dashboard
- Available, committed, in-transit, and at-risk volume by product and location.
- Days of cover under base and stress demand.
- Expected arrivals with vessel and document status.
- Average cost, replacement cost, and potential inventory exposure.
- Storage utilization, quality exceptions, and aging.
- Supplier, origin, and corridor concentration.
- Regional port-stock benchmarks for key inputs (e.g., sulfur), tracked against the prior-year comparison to flag structural rather than seasonal drawdowns.
18. Quality, Specification and Claims Management
Specification governance
Every purchase should reference an approved product specification and test method. Chemical assay alone is insufficient: physical properties determine handling, blending, and field application. Specifications should distinguish guaranteed limits, typical values, and information-only parameters.
Changes in the producer, plant, production route, or raw materials can affect performance even when the nominal grade remains unchanged. Supplier change control and sample approval are important for critical applications and branded products. A planned turnaround, followed by a restart, is a recognized moment at which a producer’s output can shift in ways not immediately visible on a certificate of analysis; specification governance should treat the resumption of production after an extended outage as a trigger for renewed sample verification rather than an automatic return to the prior approval.
Urea and nitrogen-product quality
Granular and prilled urea differ in particle size, hardness, and application behavior. Relevant parameters include nitrogen content, moisture, biuret, particle-size distribution, crushing strength, and free ammonia. Agricultural and industrial uses may require different tolerances.
Ammonium sulfate can be crystalline, compacted, or granular, depending on the production route. Nitrates and UAN require concentration and safety controls. Comparing products on price without normalizing nutrient concentration and physical form can create false savings.
Ammonia quality and reliability of supply are closely linked. A planned, multi-week turnaround at a major ammonia plant, or an extended strategic review at another, can each affect the mix of origins available to buyers over a given quarter; specification governance for ammonia-linked products should confirm current source and production status at the point of contracting rather than relying on a standing supplier list.
Sulfur and phosphate quality
Sulfur may be granular, formed, lumpy, or molten. Purity, ash, acidity, moisture, particle condition, and handling losses affect use. Dust and fines can create safety and environmental issues. Sampling a heterogeneous cargo requires an agreed and representative method.
Potash, NPK and methanol
MOP and SOP differ chemically and agronomically. Grade, potassium content, moisture, particle size, and color may affect use and customer expectations. NPK requires verification of each declared nutrient, physical uniformity, and resistance to caking and segregation.
Methanol quality is governed by purity and controlled impurities, with separate safety and handling requirements. Tank cleanliness and previous cargo are critical. Chemical contamination can render a cargo unsuitable even when quantity and delivery are correct.
Sampling, inspection and laboratories
Sampling plans should specify location, timing, increment count, composite preparation, sealing, and chain of custody. Loading inspection can prevent disputes that are difficult to resolve after discharge. Independent inspectors should be competent for the product and the port.
Laboratory methods must be named and compatible. When buyer and seller results differ, the contract should define the referee laboratory and tolerance. Retained samples should remain sealed for the duration of the claim period.
Claims process
Claims require timely notice, evidence, mitigation, and quantification. Quantity claims may depend on draft survey, shore scale, or tank measurement. Quality claims require samples, certificates, photographs, handling records, and laboratory reports. Delay claims require contractual and operational records.
Commercial teams should avoid informal settlement before technical review. The organization should record the root cause, recovery, and corrective actions to prevent recurring losses resulting from changes in supplier qualifications or contract terms. Where a claim’s timing coincides with a known supplier event — a planned turnaround, a restart, or a change of ownership review at the production facility — the root-cause analysis should explicitly consider whether that event, rather than an isolated quality lapse, explains the deviation, since the corrective action required differs materially between the two cases.
19. Risk Register and Internal Controls
| Risk | Example event | Primary control | Owner |
|---|---|---|---|
| Price | Public benchmark changes rapidly | Coverage bands and verified executable quotations | Commercial |
| Freight | Route or vessel cost rises | Alternative routes and freight clauses | Logistics |
| Supply | Official outage or export restriction | Supplier diversification and safety stock | Procurement |
| Quality | Off-spec cargo | Approved specifications and inspection | Quality |
| Credit | Customer or supplier default | Limits, security and monitoring | Finance |
| FX | Local currency depreciation | Currency matching and hedging policy | Finance |
| Compliance | A government restriction affects a party, vessel, or payment chain | Screening and legal review | Compliance |
| Operational | Port or warehouse cannot perform required handling | Capability checks and contingency plan | Operations |
Risk scoring methodology
Risks should be scored by likelihood, financial impact, operational impact, and speed of onset. A low-probability event may require strong controls if it can stop production or create legal exposure. Speed matters because some risks allow time to source alternatives while others require an immediate response — a scheduled, multi-week plant turnaround announced in advance sits at one end of that spectrum, while a same-day trade suspension between two counterparty jurisdictions sits at the other.
Scores should reflect residual risk after controls, not the uncontrolled scenario. Assumptions, evidence, and review date should be recorded. The purpose is prioritization and action rather than a mathematically precise forecast.
Price and basis risk
Price risk includes movements in the selected benchmark. Basis risk arises when the organization’s actual product, location, or timing differs from the benchmark. A hedge or formula can reduce benchmark risk while retaining exposure to freight, quality, or regional spread.
Supply-chain and geopolitical risk
Supply risk can arise from plant failures, export policy changes, maritime attacks, port closures, labor actions, weather events, or vessel shortages. Supplier diversification and inventory are common controls, but both have costs. Contingency plans should identify alternative products and destinations before a disruption occurs.
Security information should be sourced from authoritative maritime and government channels. Market rumor can guide an investigation but should not, by itself, trigger irreversible action.
Counterparty and credit risk
Supplier default can remove critical volume; customer default can convert inventory into an unplanned position. Limits should incorporate exposure, financial strength, country risk, payment security, and operational dependence. Prepayment requires particular care.
Control testing and incident review
Controls should be tested through sample transactions, document review, and scenario exercises. A policy that cannot be executed under time pressure is not an effective control. Owners should understand both the required action and the escalation route. Tabletop exercises should periodically simulate both categories of disruption observed in August 2026 — the scheduled outage that removes known volume for a known period, and the sudden counterparty or jurisdictional measure that removes volume, routes, or payment channels without notice — so that response times and decision authority are tested under both conditions rather than only the more predictable one.
After incidents, a structured review should identify the root cause, the control failure, the financial impact, and the corrective action. Lessons should be incorporated into contracts, scorecards, and training rather than remaining in a narrative report.
20. Market Monitoring and Early-Warning System
Dashboard architecture
The monitoring system should combine price, physical flow, logistics, demand, financial, and geopolitical indicators. Prices describe the outcome; physical indicators often provide earlier warning. The dashboard should show the source, timestamp, unit, and whether the data are observed, estimated, or internal.
A small set of trusted indicators is more useful than a large ungoverned feed. Each metric should have an owner, an update frequency, a threshold, and a corresponding decision. Historical values should be retained to identify regime changes.
Nitrogen indicators
- India tender announcements, awards, shipment windows, and executed volume.
- Chinese urea and phosphate export policy, inspections, and offers.
- Persian Gulf, North African, Chinese, and Atlantic production outages.
- Urea FOB/CFR benchmark spreads and destination netbacks.
- Henry Hub, TTF, and other relevant feedstock indicators.
- Brazil import pace, NOLA seasonality, and regional inventory.
Ammonia and methanol indicators
- Major plant outages, restarts, and planned maintenance.
- Specialized vessel availability and terminal schedules.
- Downstream operating rates and industrial margins.
- Gas or coal feedstock economics by production region.
- Posted prices, discounts, and realized-price evidence.
- Spread between contract settlement and prevailing spot assessment, to flag when the two series diverge materially in either direction.
Sulfur and phosphate indicators
- Persian Gulf producer prices, cargo offers, and vessel departures.
- Moroccan sulfur procurement and phosphate export programs.
- Sulfur freight by route and parcel size.
- Brazil MAP import pace and grower affordability.
Potash and NPK indicators
- Producer sales and production guidance.
- Canadian rail and terminal performance.
- Russian and Belarusian trade-route and sanctions developments.
- China and India contract negotiations.
- Brazil, Southeast Asia, and North America demand indicators.
- Raw-material replacement cost for major NPK formulations.
Logistics and security indicators
IMO, flag-state, insurer, and trusted security updates should be distinguished from commercial market commentary. The dashboard should highlight changes that affect crew safety, legal transit, or insurance rather than attempt to predict political outcomes.
Alert levels
A green status indicates normal monitoring and approved coverage. Amber indicates a threshold breach that requires review—such as widening freight, delayed vessels, or falling inventory. Red indicates a confirmed condition requiring action, such as loss of a supplier, closure of a route, or breach of minimum stock.
Alerts should have expiry and review times. Without closure rules, dashboards remain permanently amber and lose value. Every red alert should record management action and communication.
21. Commercial Decision Framework
Buy, wait, or split
A buy decision is appropriate when the physical requirement is firm, coverage is below target, or execution risk outweighs the potential price decline. Waiting is appropriate when stock is sufficient, offers are poorly executable, or downside evidence is strong. Splitting reduces timing risk and is often the default under uncertainty.
The chosen action should specify the quantity, price basis, window, origin, expected landed cost, scenario, and invalidation trigger. This allows for later evaluation of decision quality rather than judging solely by the price outcome.
Supplier allocation decision
Allocation should consider the risk-adjusted total value—price, quality, reliability, documentation, compliance, freight, and relationships all matter. A weighted score can support judgment, but weighting should reflect product criticality and be approved before bids are opened.
New suppliers may receive trial quantities with enhanced inspection. Strategic suppliers may receive a base allocation while competing for additional volume. Poor performance should have a documented consequence.
Sales and customer strategy
Sales commitments should be aligned with procurement and logistics. Fixed-price sales against floating purchases create risk, while destination commitments can become unprofitable if freight rates change. Contracts should reflect the organization’s ability to source and deliver.
Investment and capability decisions
Persistent logistics or quality constraints may justify investment in storage, bagging, blending, terminals, laboratory capability, or digital monitoring. The business case should compare capital cost with avoided demurrage, lost sales, inventory reduction, and resilience.
Decision record template
- Business requirement and deadline.
- Options considered and normalized landed cost.
- Key risks, scenarios, and triggers.
- Selected action, owner, and approvals.
- Expected cash and margin effect.
- Review date and actual outcome.
Final management perspective
The fertilizer and petrochemical markets covered in this report are subject to structural volatility due to the interplay among energy, agriculture, policy, and maritime trade. The organization cannot control these drivers, but it can control data quality, portfolio design, contract clarity, inventory discipline, and response speed.
22. Product-Specific Procurement Strategies
Urea strategy
Urea procurement should balance tender-driven global volatility with broad availability of origins. Base requirements can be covered through qualified term suppliers, while seasonal or customer-linked volume is staggered across shipment windows. Persian Gulf offers should be evaluated based on route execution, while Atlantic and Chinese alternatives should be compared on a normalized delivered-value basis.
The buyer should track granular versus prilled specification, agricultural versus industrial requirements, parcel size, and destination. A low FOB price is not preferable when freight costs, delays, or quality issues increase the expected cost. India’s tender pace and the Persian Gulf transit position should both be reflected in the coverage bands, alongside Brazil’s demand scenarios.
Ammonia strategy
Ammonia requires terminal and vessel compatibility, making supplier substitution slower than for dry bulk. Procurement should secure a reliable core schedule and maintain technically qualified alternatives. Contract formulas should match the relevant regional benchmark and freight basis.
Outage response plans should include inventory, substitute downstream feedstocks where technically possible, terminal slots, and gas-carrier availability. Low-carbon ammonia should be contracted under a separate certification and carbon-intensity framework.
Sulphur strategy
Sulfur coverage should be tied to the criticality of downstream plants. A phosphate producer may accept a higher inventory cost to avoid shutdown. Supplier diversification should span the Persian Gulf and alternative origins where quality and freight permit. Freight capacity may need to be secured with the commodity rather than afterward.
DAP, MAP and phosphate strategy
Phosphate procurement should monitor sulfur, ammonia, and destination demand rather than rely only on the finished benchmark. India-linked DAP and Brazil-linked MAP require different timing and commercial structures. Buyers should qualify Morocco, the Persian Gulf, China, and other origins according to specifications and routes.
Potash strategy
Potash’s relative stability supports normal coverage, but concentration and long logistics require planning. MOP and SOP must be managed separately. Canadian reliability, the complexity of Russian and Belarusian compliance, and regional contracts should be considered when allocating suppliers.
Price-sensitive negotiations should use licensed benchmarks. Public producer guidance can support the market view but is not a substitute for exact spot evidence. Buyers should avoid building inventory solely because annual demand is forecast to grow.
NPK and methanol strategy
NPK should be purchased based on verified formula, quality, and cost per usable nutrient. Where blending capability exists, the buyer can compare finished-product imports with locally manufactured goods from raw materials, and the input-cost side of that comparison should account for any policy changes affecting the economics of sulfur or sulphuric acid, such as the Indian subsidy proposal under review in August 2026. Seasonal delivery and caking risk influence the economic quantity.
Methanol procurement should separate posted reference, discount, freight, and realized landed cost, applying the same contract-versus-spot discipline used for ammonia given the two products’ shared feedstock exposure. Terminal compatibility, tank availability, previous cargo, and safety documents must be confirmed. Currency risk is material when formulas use European or local references.
23. Route and Logistics Reference Guide
Persian Gulf to Asia
Persian Gulf to Europe and the Americas
North Africa and Mediterranean routes
North African nitrogen and phosphate producers retain relatively direct access to Mediterranean and European markets, along with competitive Atlantic routings for cargoes moving further afield. Port performance, parcel size, and product programs continue to shape actual availability more than published capacity figures. Morocco’s sulfur imports and phosphate exports remain a two-way bulk logistics flow that should be planned as a single system rather than two independent trades, since backhaul economics on both legs affect the freight quoted for either.
Mediterranean routes can also serve as an alternative when trade through the Red Sea or the Persian Gulf is disrupted, since several North African and southern European load and discharge points lie outside those chokepoints. However, regional port congestion, seasonal vessel demand, and now inland barge constraints on the Rhine should all be monitored together; a Mediterranean routing that avoids one bottleneck can still be exposed to another further along the supply chain.
Baltic and Black Sea routes
Commercial advantages on these routes must still be adjusted for sanctions exposure, banking-chain acceptance, insurer willingness, vessel ownership, and physical security considerations that can change with limited notice. Documentation and payment-chain confirmation should occur before a fixture is finalized rather than after; route or port substitution following contract signature can alter duty treatment, sanctions analysis, and freight responsibility in ways that are difficult and costly to unwind once cargo is loaded.
Canada and the Pacific
Canadian potash and sulfur exports depend on rail transport to coastal export terminals and then on long-haul ocean routes to Asia or Latin America. Mine output, railcar availability, terminal storage capacity, weather, and wildfire risk are all linked, and a purely inland disruption can affect ocean delivery schedules even when the vessel market itself is fully available.
Buyers should track actual rail and terminal performance alongside annual producer guidance, since the two frequently diverge during periods of weather stress or labor disruption. For critical delivery windows, maintaining an alternative terminal or origin capability carries strategic value that is difficult to quantify in a single freight comparison but material in a supply-continuity assessment.
Destination-port readiness
Logistics plans should account for holiday calendars, seasonal weather windows, port congestion trends, document cutoff times, and emergency contact chains for every active route. Destination-side failures can erase savings achieved through careful commodity and freight negotiation, and in the current environment, a well-negotiated cargo that queues for two additional weeks at a congested discharge port can end up costing more than a slightly higher-priced cargo delivered on schedule.
Route comparison checklist
- Named loading and discharge ports, not only regions.
- Product, parcel size, and compatible vessel class.
- Expected sailing time and named route alternatives, including Cape and Panama contingencies.
- Vessel flag, beneficial ownership, and insurer acceptance for the specific routing.
- Port costs, expected waiting times, and demurrage terms, adjusted for current congestion risk.
- Inland leg cost and capacity, where barge or rail movement follows the ocean leg.
- Banking, sanctions, and documentation requirements confirmed before fixture.
- Probability of on-time delivery to the business-need date, not just the nominal laycan.
24. Financial KPIs and Performance Measurement
Procurement KPIs
Logistics KPIs
A lower freight rate that results in higher demurrage or late-delivery losses is not an improvement and should not be reported as one. Total logistics cost and service level should always be evaluated together, with the freight KPI and the on-time-delivery KPI presented side by side rather than in isolation.
Inventory KPIs
Margin and working-capital KPIs
Risk and control KPIs
Risk metrics include volume sourced from top origins and suppliers, unhedged foreign-exchange exposure, uninsured cargo exposure, sanctions-screening exceptions, overdue claims, red-level alerts, and unresolved control actions. A risk KPI should trigger ownership and review, not remain a passive descriptive figure in a report that no one is required to act on.
Balanced scorecard
A balanced commercial scorecard should combine cost, service, quality, cash, and risk into a single management view. Overweighting cost alone encourages fragile decisions — for example, selecting the cheapest available Persian Gulf-origin freight without regard to the delivery-probability gap documented in this report’s route guide. Overweighting security alone can lead to excess inventory and eroded margins. Management should approve explicit weights based on strategy and the criticality of each product line, and should revisit those weights when conditions change materially.
Sources & References
- World Bank Commodity Markets Pink Sheet — September 2026
- US EIA Short-Term Energy Outlook — August 2026
- Nutrien Second-Quarter 2026 Results
- Mosaic Second-Quarter 2026 Results filed with the SEC
- Methanex Historical Posted Prices — August 2026
- UAE Ministry of Foreign Affairs statement — 19 August 2026
- Panama Canal operating announcement published in August 2026
- CF Industries Blue Point One announcement
- CHS and OCP North America Waggaman announcement
- India RCF August 2026 tender public notice coverage